
One equation explains most of it
At a 5% cap rate, 60% loan-to-value and 4% debt, the equity return is about 6.5%: cap rate plus leverage times the spread. Positive leverage becomes negative the moment debt costs more than the cap rate.
A property's unlevered return is roughly its cap rate. Lever it and the equity return becomes:
At a 5% cap rate, a 60% loan-to-value and a 4% debt cost, the equity return is 5% + 1.5 × 1% = 6.5%.
The equation is simple and it explains the two things that surprise people about property returns: why leverage matters so much, and why it cuts both ways.
What the equation says
The spread is what gets multiplied. A 100 basis point gap between cap rate and debt cost becomes 150 basis points of extra equity return at 60% LTV. At 75% LTV, the multiplier is 3, and the same gap becomes 300 basis points.
Leverage does nothing when the spread is zero. If the debt costs exactly the cap rate, the equity return equals the cap rate regardless of LTV.
Positive leverage becomes negative leverage when the debt costs more than the cap rate. In a rising rate environment, a property bought at a 4.5% cap with 6% debt has a negative spread, and more leverage makes the return worse.
What the leverage test has to show
A property model that claims a levered return has to show the pieces.
LTV times value equals debt. The loan amount is a percentage of the purchase price or the appraised value, and which one it is has to be stated. A model that uses one for the loan and the other for the return computation is inconsistent. A corporate model enforces the same consistency through its financing-structure linkage, where the debt share is set once.
Debt service is covered by NOI. DSCR, NOI over annual debt service, is the covenant that decides whether the loan survives a bad year. A model that reports a levered return without a DSCR has not modeled the loan.
The cash-on-cash return reconciles to the equity check. Cash flow after debt service divided by equity invested must equal the return the model reports. If it does not, something is being counted twice or missed.
What the equation hides
Amortization. The equation assumes interest-only debt. An amortizing loan repays principal, which builds equity and changes the return over time, usually upward for the equity holder.
Exit. The leveraged return at exit is not the same as the current cash yield. A sale at a different cap rate than the purchase produces a capital gain or loss that leverage also multiplies.
Costs. Acquisition costs, financing fees and capex are all outside the equation and all reduce the return.
Recourse and covenants. A model can produce a positive return right up to the point the DSCR covenant trips, at which point the equity is gone. The arithmetic does not show that boundary.
Why the workbook has no property model
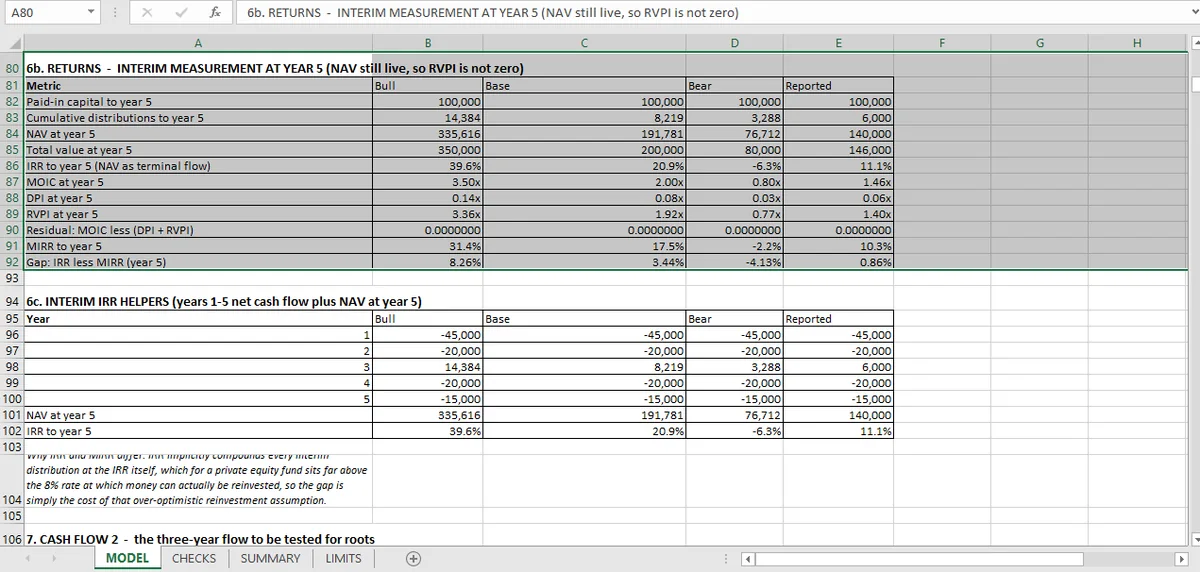
This series models a fund of companies, rounds and a waterfall, not a building. There is no property, no cap rate and no loan in it, and the limits sheet does not claim otherwise.
What the workbook does have is the discipline this equation needs: every reported return is rebuilt from its components. The multiple identity does the same job for MOIC, DPI and RVPI, and the waterfall article shows how a distribution gets split once the return is computed.
The equation is worth keeping in mind for any property model: if the reported equity return cannot be reproduced from the cap rate, the LTV and the debt cost, one of the three is not what it claims to be. The exit value that return feeds is in the property DCF, and the fund-level split is in the integration piece.
The Mica workbook holds the cap rate, the LTV and the debt cost as separate inputs, which is what makes the leveraged return rebuildable. Keeping those three apart is the separate-input layout that makes the rebuild possible.